
Selling your HDB flat for S$700,000 does not mean you will receive S$700,000 in cash.
Before deciding how much you can put towards your next home, it is important to work out your estimated net sale proceeds.
The basic calculation is:
Selling price − outstanding housing loan − required CPF refund − other selling expenses = estimated cash proceeds
Step 1: Start With Your Expected Selling Price
Your selling price is the amount agreed between you and the buyer.
Before setting an asking price, compare your flat with recent transactions for similar units nearby, taking into account factors such as flat type, floor level, remaining lease and condition.
RealValue Instant Valuation can provide an initial valuation reference and recent transaction data before deciding how to position your flat.*
Step 2: Deduct Your Outstanding Housing Loan
Your sale proceeds are first used to repay any outstanding HDB or bank housing loan.
According to CPF Board’s guidance on property sale proceeds, the outstanding housing loan takes priority before the required CPF refund and other sale expenses.
So if your flat sells for S$700,000 and you still owe S$200,000, the remaining amount before other deductions is S$500,000.
Step 3: Deduct Your Required CPF Refund
If you used CPF savings to buy the flat or pay your mortgage, you generally need to return the CPF principal amount used plus accrued interest when you sell.
This includes any CPF housing grants you received, as the grants are credited to your CPF account and treated as part of your principal withdrawal.
Accrued interest is the interest your CPF savings would have earned if the money had remained in your CPF account instead of being used for the property.
You can check your estimated refund through the “What Happens If” section of your CPF Home ownership dashboard. See CPF Board’s housing refund guidance for details.
The CPF refund goes back into your CPF accounts — it is not a fee paid to HDB.
For sellers aged 55 and above, the refunded amount may first be used to top up the Retirement Account (RA) to the applicable Full Retirement Sum (FRS) before any remaining amount stays in the Ordinary Account, subject to prevailing CPF rules.
Step 4: Account for Other Selling Costs
Other expenses can reduce the amount of cash you eventually receive.
These may include legal fees, mortgage discharge fees, property tax, service and conservancy charges, and agent fees if you engage a salesperson.
HDB’s resale completion guidance explains that legal costs depend on whether HDB or a private solicitor acts for you. Sellers must also settle property tax and service and conservancy charges as required.
A Simple Example
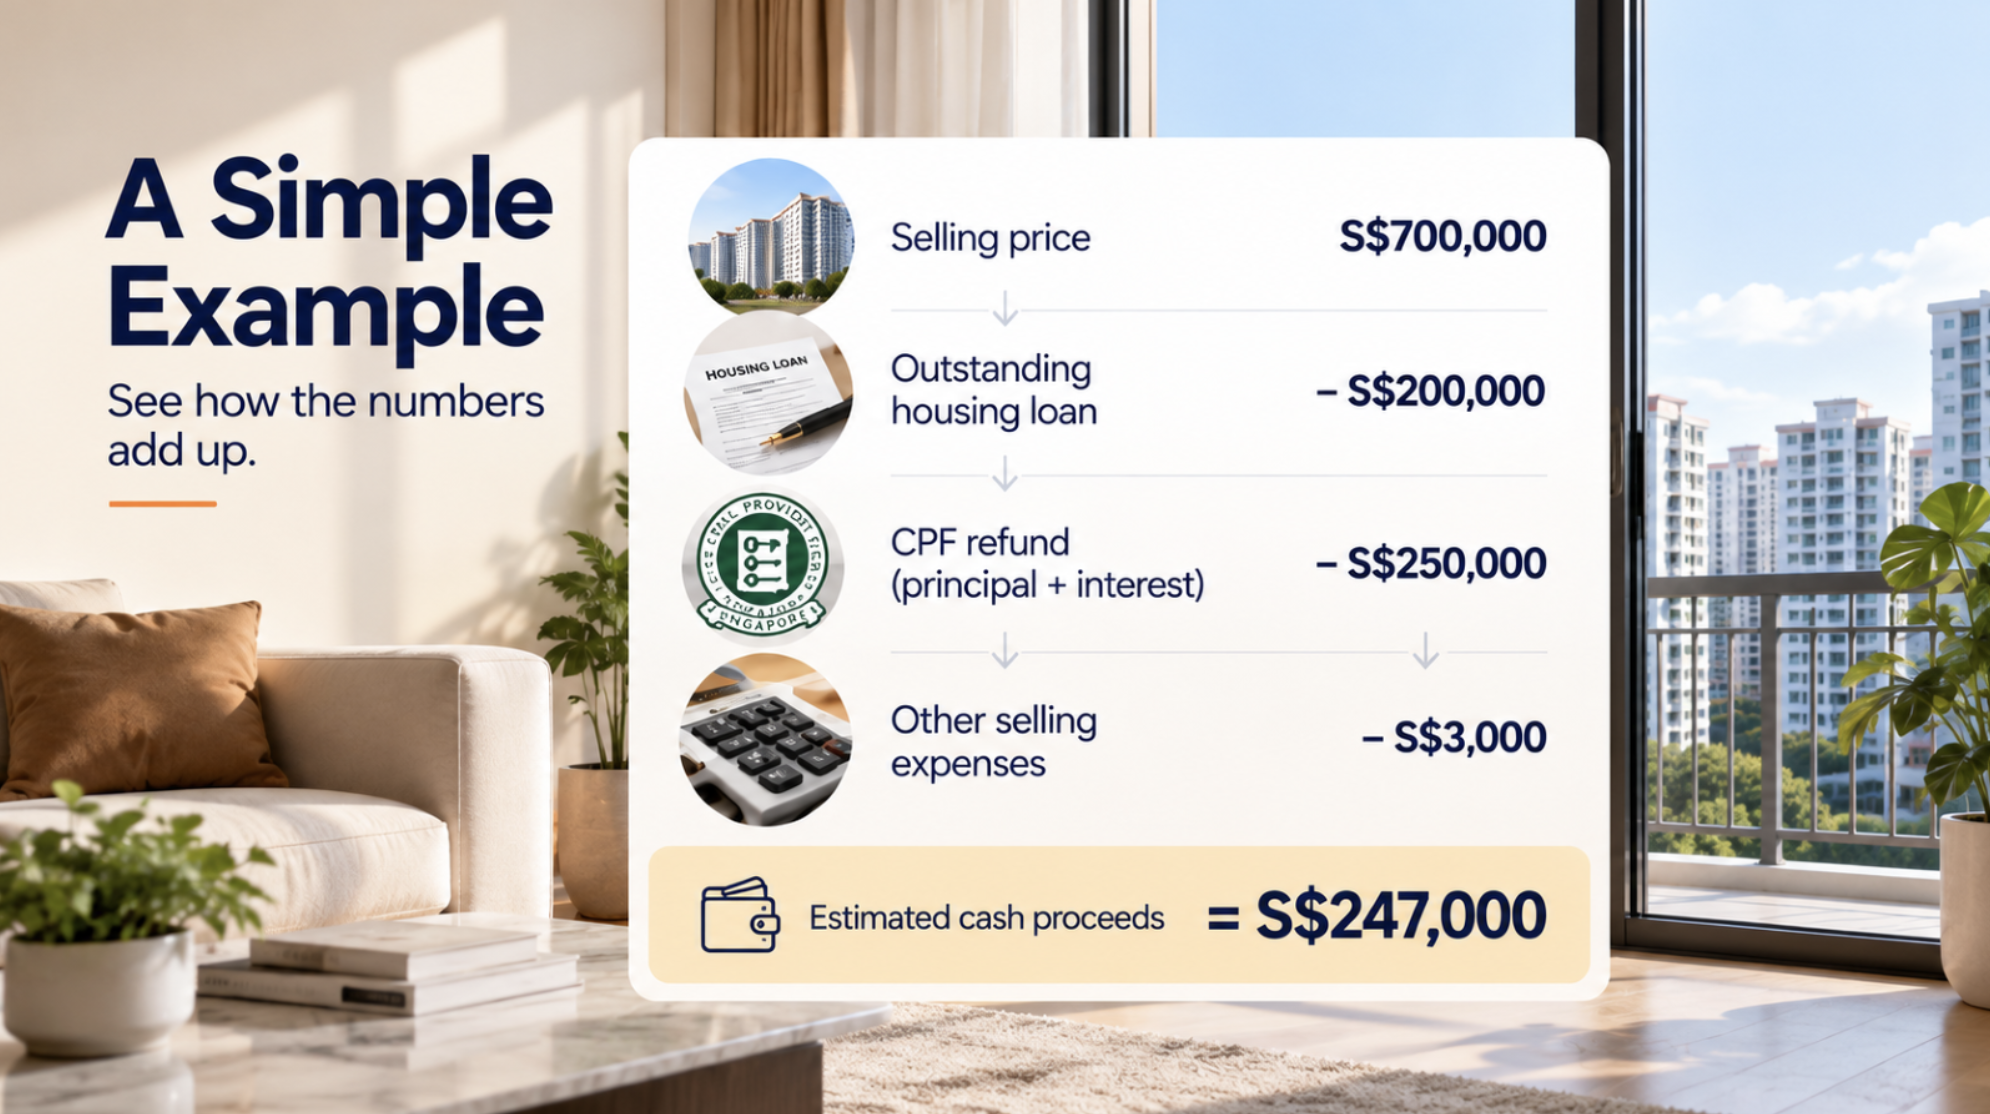
Suppose your numbers look like this:
Selling price: S$700,000
Outstanding housing loan: S$200,000
Required CPF refund: S$250,000
Other selling expenses: S$3,000
Your estimated cash proceeds would be:
S$700,000 − S$200,000 − S$250,000 − S$3,000 = S$247,000
So although the flat sells for S$700,000, approximately S$247,000 would remain as cash proceeds in this simplified example.
What If Your Sale Proceeds Cannot Cover the Full CPF Refund?
If you sell the flat at market value and the proceeds are not enough to cover both your outstanding housing loan and required CPF refund, you generally do not need to top up the CPF shortfall in cash.
Instead, the remaining proceeds after paying off the housing loan are refunded to CPF. Any option monies received from the buyer are also treated as part of the selling price and may need to be refunded.
You can refer to CPF Board’s guidance on property sale shortfalls for the latest rules.
The Bottom Line
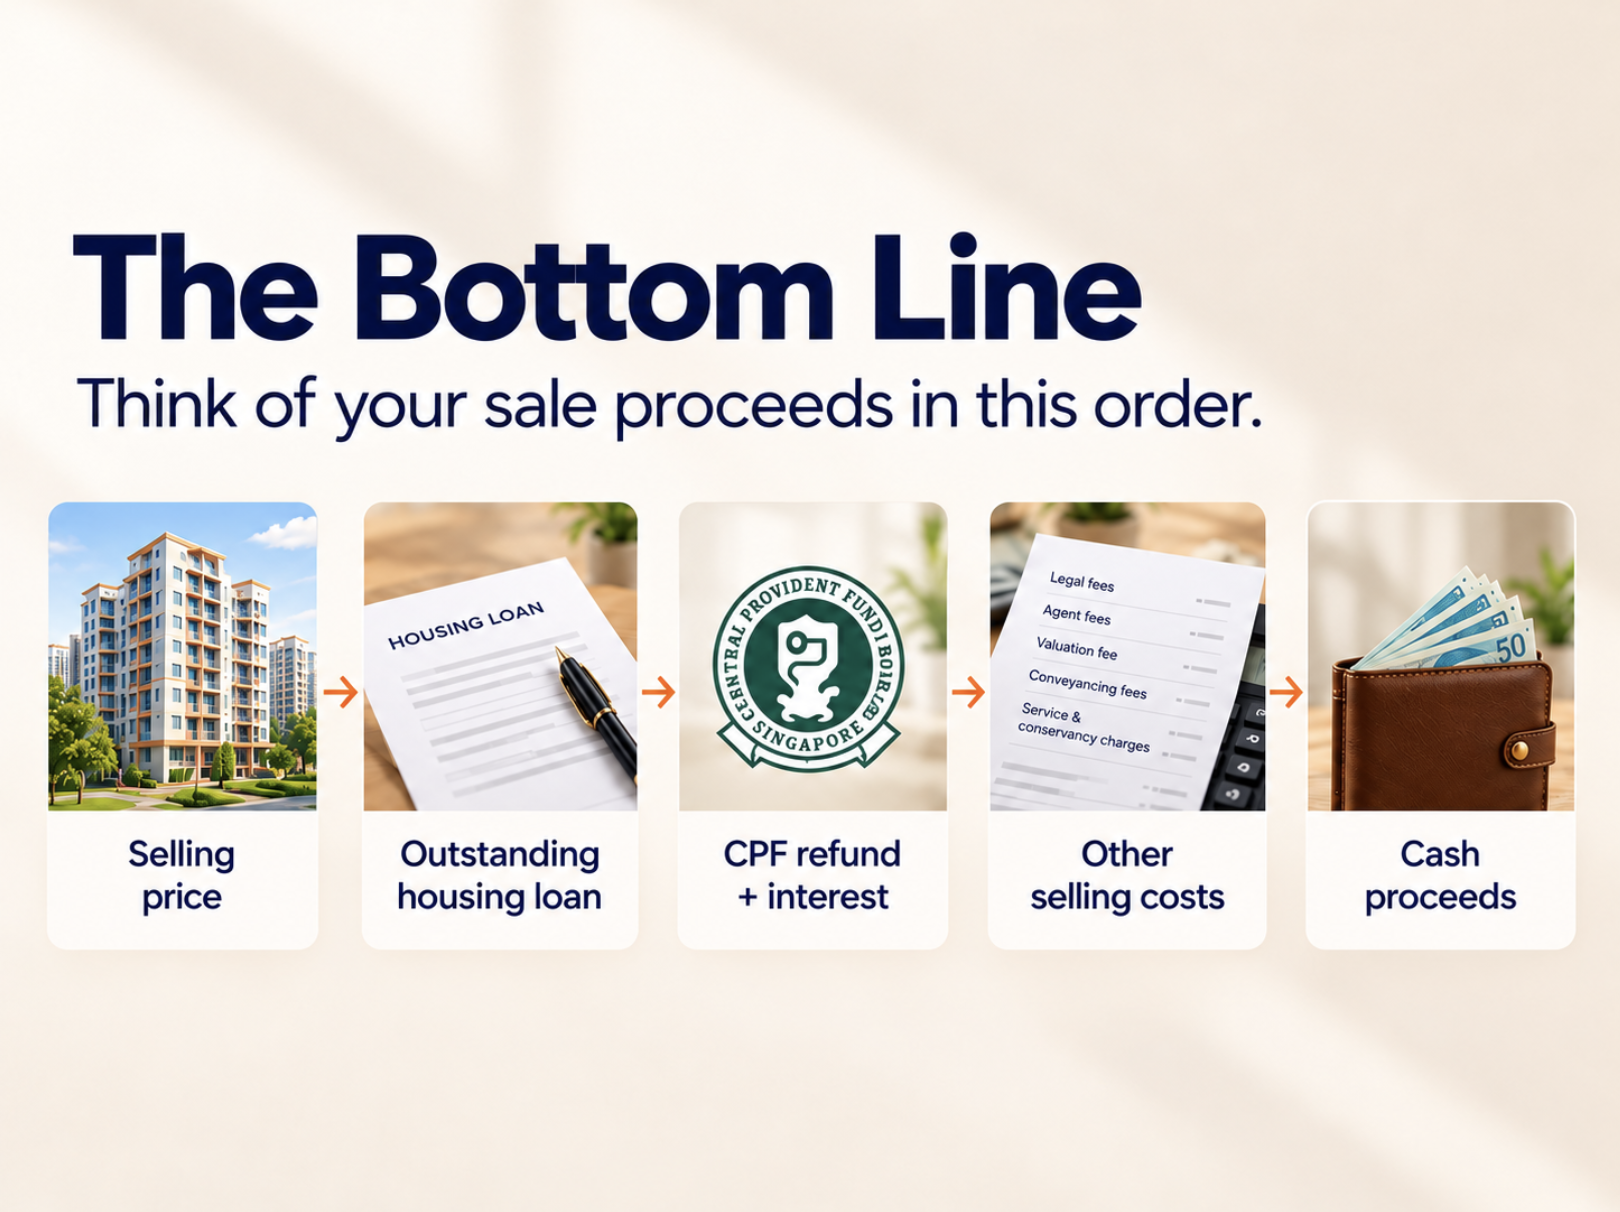
Before selling your HDB flat, think about the proceeds in this order:
Selling price → outstanding loan → CPF refund → selling costs → cash proceeds
Working out these numbers early can help you avoid overestimating how much cash you will have available for your next property.
Disclaimer: HDB and CPF rules used in this article are accurate as of 29 October 2026 and may change. Always check the latest CPF housing refund guidance and HDB resale guidance before committing to a sale.
Share this article


